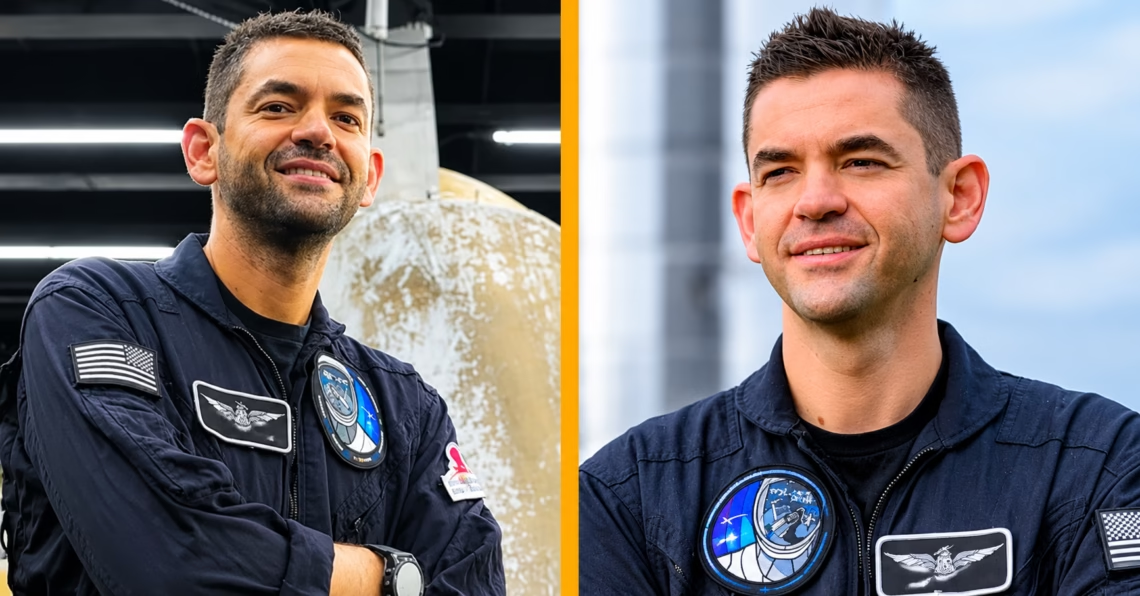
Jared Isaacman Harbortouch is a search topic that connects entrepreneur Jared Isaacman with Harbortouch, a payment processing and point-of-sale technology business that played an important role in his professional journey. Before becoming widely recognized for aviation, private spaceflight, and his leadership at NASA, Isaacman built his reputation as a young entrepreneur in the financial technology industry.
His business story began in 1999, when he founded United Bank Card at just 16 years old. The company grew from a small operation into a major payment processing business, later becoming associated with the Harbortouch name and the broader corporate development that led to Shift4 Payments. Its growth illustrates how a business can evolve by adapting to merchant needs, improving technology, and expanding its services over time.
Harbortouch is an important part of this story because it represents a stage in the development of Isaacman’s original business. The company focused on helping merchants accept payments and manage everyday operations through payment terminals, electronic cash registers, and point-of-sale systems. These services addressed practical problems faced by restaurants, retailers, and other small and medium-sized businesses.
Understanding the connection between Jared Isaacman and Harbortouch requires looking beyond a simple company name. It involves his early entrepreneurial decisions, the changing payment technology market, the company’s growth strategy, and the relationship between traditional payment processing and modern commerce platforms.
This article explores Jared Isaacman’s background, how Harbortouch fits into his business history, what the company offered, why its business model mattered, and how this experience contributed to his broader career.
Who Is Jared Isaacman?
Jared Isaacman is an American entrepreneur, aviator, commercial astronaut, and public figure known for building a successful payment processing business and pursuing ambitious projects in aviation and spaceflight.
Born on February 11, 1983, Isaacman demonstrated an interest in business from an early age. Rather than following a conventional educational and professional path, he began exploring opportunities to establish his own company while still a teenager.
His most significant early business achievement was founding United Bank Card in 1999. The business operated in the merchant payment processing industry, which helps companies accept card payments from customers. What began as a small entrepreneurial venture eventually developed into a much larger payments technology operation.
Isaacman’s career later expanded into aviation. He developed significant flying experience, participated in high-profile flight projects, and became involved in commercial spaceflight. He also founded Draken International, an aviation and defense services company known for providing adversary air training to military organizations.
These different activities make his career unusual. Payment processing, military aviation services, and human spaceflight operate in very different industries, but each involves technology, operational planning, and the ability to manage complex projects.
For readers searching for Jared Isaacman Harbortouch, however, the payment processing business remains the most relevant starting point. It was the foundation of his entrepreneurial career and a major part of the professional experience that preceded his later public recognition.
What Is the Connection Between Jared Isaacman and Harbortouch?
Jared Isaacman is connected to Harbortouch through the payment processing company he founded as a teenager. His original business was known as United Bank Card, and it later became associated with the Harbortouch brand.
Harbortouch provided merchant services and point-of-sale technology to businesses across the United States. Its offerings helped merchants accept electronic payments, operate checkout systems, and manage transactions through integrated hardware and software.
Isaacman played a central leadership role in developing the business. His early focus was on improving the way payment processing services were delivered to merchants. Instead of treating payment acceptance as an isolated service, the company developed solutions that brought payment terminals and business management tools together.
This approach was relevant to merchants that wanted to simplify their daily operations. A restaurant, for example, might need to accept credit cards, track orders, manage tables, and reconcile sales. A retail shop might need a checkout terminal, an electronic cash register, and reliable transaction reporting. Combining these functions can make daily business management easier.
Harbortouch became a recognizable name in the point-of-sale market, while the broader business continued to evolve through corporate changes, acquisitions, and expansion.
The relationship is best understood as part of a longer company history. United Bank Card was the original business Isaacman founded. Harbortouch represented a significant stage in the development of that business, and Shift4 Payments became the modern corporate identity associated with its wider evolution.
This distinction matters because the names do not always represent three completely unrelated businesses. They reflect different stages, brands, and corporate developments within the broader history of Isaacman’s payment processing enterprise.
How Jared Isaacman Started His Business at Age 16
One of the most remarkable parts of Isaacman’s story is how early he entered the business world.
In 1999, when he was 16, he founded United Bank Card from his parents’ basement in New Jersey. At an age when most teenagers are concentrating on school and planning their first jobs, he was working to establish a company in a competitive financial services industry.
Isaacman had first gained experience in the credit card processing business by working for another company in the industry. That experience helped him understand how merchant payment services operated and where existing practices could be improved.
He identified an opportunity in the process of helping businesses accept card payments. Merchants needed payment processing services, but onboarding procedures, equipment costs, and administrative requirements could make the process inconvenient.
For a small business, setting up a payment system is not simply a technical decision. Owners must consider fees, equipment, contracts, transaction reliability, and customer convenience. Complicated applications or expensive equipment can create additional barriers, particularly for businesses with limited budgets.
Isaacman’s business aimed to compete by making payment services more accessible and convenient. Rather than beginning with a large office, a substantial workforce, or an established national brand, the company started with a small operation and a specific commercial opportunity.
The early years required persistence. A new payment processing business must earn merchants’ trust, establish relationships with financial institutions, maintain reliable systems, and compete with established providers. Growth depends not only on attracting customers but also on serving them consistently.
United Bank Card gradually expanded its operations and customer base. Its later development into the Harbortouch business demonstrated that the original venture had moved well beyond its modest beginnings.
The lesson from this stage of Isaacman’s career is not simply that he started young. It is that he entered a complex industry, learned how its commercial processes worked, identified customer problems, and built a business around addressing them.
What Was a United Bank Card?
United Bank Card was the original payment processing business founded by Jared Isaacman in 1999. Its central purpose was to help merchants accept electronic payments from customers.
Payment processing is an essential part of modern commerce. When a customer pays with a credit or debit card, several parties work together to authorize and complete the transaction. A merchant needs the appropriate equipment, a payment processing arrangement, and systems that can communicate with the relevant financial networks.
Payment processors help coordinate these activities. Depending on the provider and service arrangement, merchants may also receive support with transaction reporting, account management, payment terminals, and other operational requirements.
United Bank Card entered this market with a focus on merchant services. Its customers needed practical ways to accept card payments without adding unnecessary complexity to their businesses.
As the company expanded, its services and business model developed beyond the needs of a small startup. It served a growing merchant base and moved toward integrated payment and point-of-sale solutions.
The business also benefited from the wider shift toward electronic payments. As consumers increasingly used payment cards, merchants needed reliable ways to accept them. Restaurants and retailers, in particular, had to combine payment acceptance with fast checkout processes and accurate sales records.
United Bank Card’s growth illustrates the importance of solving a recurring commercial problem. Merchants do not purchase payment technology simply because it is new. They need systems that work reliably, support their business operations, and make it easier for customers to complete purchases.
The company eventually became known as Harbortouch, marking an important development in its identity and service offering.
How United Bank Card Became Associated With Harbortouch
The development from United Bank Card to Harbortouch was part of the company’s broader expansion in payment processing and point-of-sale technology.
The Harbortouch name became associated with a more recognizable business offering that combined merchant payment services with hardware and software for daily operations.
This change reflected the growing importance of integrated business technology. Payment processing was no longer only about transmitting a card transaction. Merchants increasingly wanted systems that could support checkout, order management, reporting, and other routine tasks.
Harbortouch developed its presence in this market by offering point-of-sale systems and related merchant services. The brand became particularly relevant to businesses that needed more than a basic card reader.
Restaurants, bars, retail stores, and other merchants often have different operational requirements. A restaurant may need table management and order routing, while a retail store may prioritize inventory tracking and efficient checkout. A useful point-of-sale platform must accommodate these differences.
Harbortouch’s business model focused on providing solutions for these practical needs while remaining connected to payment processing.
The company also became known for equipment programs designed to reduce the initial cost of adopting certain point-of-sale systems. Such offers can make technology more accessible to smaller businesses, although the actual terms, service obligations, and processing costs depend on the agreement.
For Isaacman, Harbortouch represented a significant phase in building a payment services business that could compete through a combination of processing, technology, and merchant support.
It is important to avoid describing the corporate history as a single, uncomplicated name change. The organization went through several stages of development, and Harbortouch remained an important brand within the broader business that ultimately became associated with Shift4 Payments.
Read more: TikTok Emojis: All Secret Emoji Codes, Meanings, and How to Use Them
What Did Harbortouch Do?
Harbortouch focused on point-of-sale technology and payment processing solutions for businesses. Its products and services were designed to help merchants accept customer payments and manage transactions as part of their everyday operations.
The company served a market in which reliability, ease of use, and operational efficiency are important. A payment terminal that works well during a busy sales period can help a merchant maintain a smooth checkout experience. A connected point-of-sale system can also reduce the need to manage separate tools for different tasks.
Harbortouch’s offering included several major areas.
Credit and Debit Card Processing
Payment processing was a core part of the business. Merchants use payment processing services to accept eligible credit and debit card transactions.
A typical transaction involves the customer’s card or digital payment method, the merchant’s terminal or checkout system, and the financial networks that authorize and settle the payment.
Businesses depend on this process because payment delays or system interruptions can affect sales and customer satisfaction. A merchant services provider therefore needs to support dependable transaction handling and help customers resolve processing issues.
The precise fees and service terms vary by merchant agreement, transaction type, and other factors.
Point-of-Sale Systems
Point-of-sale systems, commonly called POS systems, help businesses record and manage sales. Depending on the product, they may include a touchscreen terminal, payment hardware, business software, and connected reporting tools.
A POS system can make checkout easier by combining transaction entry and payment acceptance within a single workflow.
For a retail store, the system may support product selection and sales records. For a restaurant, it may help employees enter orders, organize tables, and send information to the kitchen.
Harbortouch built its business around this type of integrated merchant technology.
Payment Terminals and Hardware
Merchants need hardware that can securely accept supported payment methods. Payment terminals connect the checkout process to the processing service.
The equipment used by a business depends on its environment and needs. A small shop may use a compact terminal, while a busy restaurant may need several checkout stations and additional devices.
Hardware availability, compatibility, and replacement arrangements depend on the particular service package.
Electronic Cash Registers
Electronic cash registers provide a way to record sales and manage basic checkout activity. More advanced systems can connect cash register functions with payment processing and reporting tools.
For businesses moving away from manual records, these systems can improve consistency and make it easier to review sales activity.
Restaurant and Retail Technology
Different industries need different features. Restaurants may require menu management, order handling, table service, and coordination between front-of-house staff and kitchen employees.
Retail businesses may prioritize product records, checkout speed, sales reports, and inventory-related functions.
Harbortouch offered solutions for several merchant categories, including hospitality and retail. This broader focus allowed the brand to serve businesses with different workflows rather than relying on a single generic payment device.
Merchant Support and Service
Payment technology requires more than equipment. Merchants may need installation assistance, employee training, account support, troubleshooting, and help understanding transaction records.
Support becomes particularly important when a business relies on its POS system throughout the working day. A malfunction can disrupt sales and create frustration for both staff and customers.
Service availability and support commitments depend on the applicable agreement, but merchant support remains an important consideration when evaluating any payment provider.
Overall, Harbortouch’s offering combined the infrastructure for accepting payments with tools intended to make everyday business management more practical.
Why Harbortouch’s Business Model Mattered
Harbortouch operated in a competitive industry where merchants often compare providers based on processing fees, equipment costs, service quality, contract terms, and available features.
Its emphasis on combining payment processing with point-of-sale technology was important because many businesses need both capabilities.
A standalone payment terminal can complete a transaction, but it may not provide the tools a merchant needs to manage orders, organize sales, or review business performance. An integrated POS system can connect these activities and reduce the effort required to maintain separate systems.
The business model also addressed the financial concerns of small and medium-sized businesses. Purchasing a complete POS setup can require an upfront investment, and smaller merchants may have limited resources for technology upgrades.
Equipment programs that reduce initial expenses can make adoption easier. However, merchants must examine the full agreement rather than judging an offer by the advertised equipment price alone. Processing rates, recurring charges, contract duration, termination conditions, and support terms can affect the total cost of ownership.
This balance between accessibility and long-term value is central to the merchant services industry.
Harbortouch also operated in a market where customer relationships matter. Businesses want payment providers that can handle transactions reliably and respond when problems occur. Strong technology must be supported by clear communication and dependable service.
From a business perspective, the model illustrates how a provider can differentiate itself by combining several related services. Instead of competing only on payment processing, a company can offer a more complete solution for the operational needs of merchants.
That broader approach helped establish Harbortouch as an important part of Isaacman’s entrepreneurial story.
Jared Isaacman’s Leadership at Harbortouch
Isaacman’s leadership was central to the growth of the business he founded. Building a payment processing company required more than identifying a market opportunity. It required developing the systems, partnerships, personnel, and operating practices needed to serve an expanding customer base.
In the early stages, a founder often handles a wide range of responsibilities. These may include sales, customer relationships, business planning, hiring, and decisions about how to allocate limited resources.
As a company grows, leadership responsibilities change. The organization must establish repeatable processes, recruit experienced managers, maintain service quality, and make decisions that support long-term development.
Payment processing adds further complexity because merchants depend on secure and reliable transaction systems. Providers must manage operational risks, comply with applicable requirements, maintain relationships with financial institutions, and respond to changes in payment technology.
Isaacman’s business developed over many years, moving from a small startup into a much larger operation. That growth required the organization to evolve beyond the methods that worked during its earliest period.
His experience demonstrates the importance of adapting leadership to a company’s changing needs. A small company may initially succeed through speed and personal involvement, but a larger organization requires structured management, specialized teams, and consistent operational standards.
Isaacman’s later involvement in other industries suggests that he was willing to pursue new challenges beyond the payment processing business. Nevertheless, Harbortouch remains relevant when examining how his entrepreneurial career began and developed.
The most meaningful aspect of his leadership story is the long-term process of building a business in a competitive industry, rather than any single achievement or company milestone.


One comment on “Jared Isaacman Harbortouch: The Business Story Behind His Success”